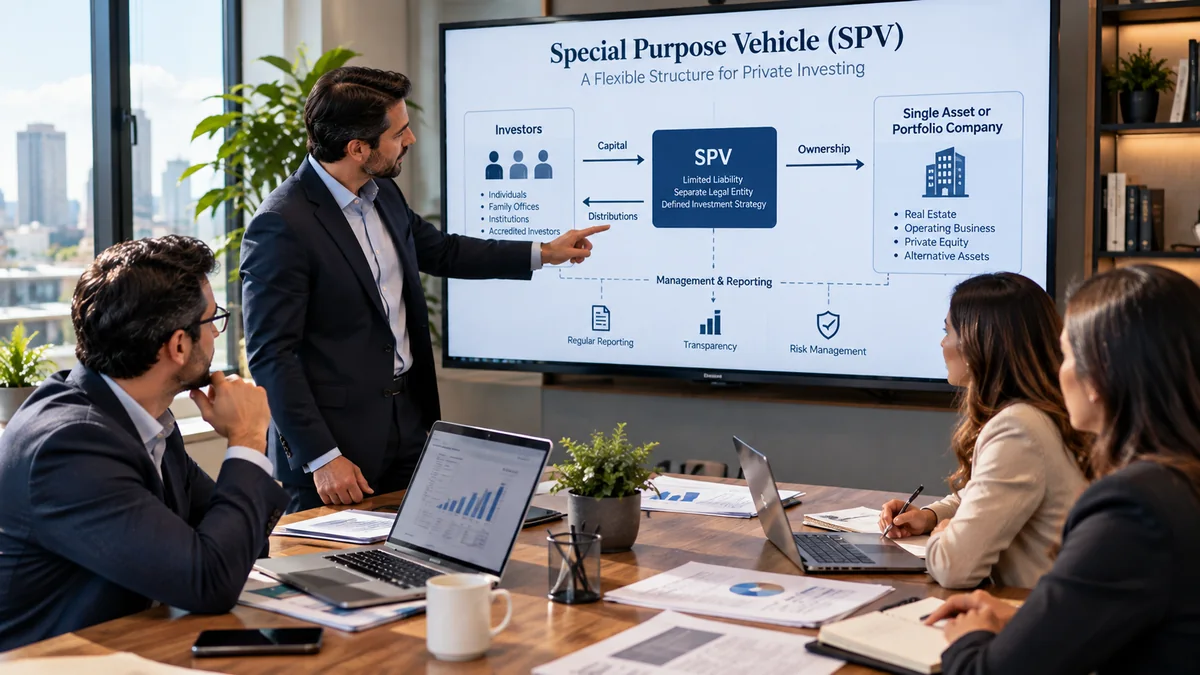
Private-market investors often encounter opportunities offered through a limited liability company or limited partnership created for one defined purpose. That structure is commonly called a special purpose vehicle (SPV). An SPV can pool capital from multiple investors and use that capital to hold a specific company, real-estate project, credit position, or another private asset.
Mack Capital’s current Fund Services division includes LLC, LP, SPV, REIT, and offshore-entity structuring, while its Investor Portal is designed to give accredited investors access to offering materials across private-market opportunities.
What an SPV Is – and What It Is Not
An SPV is a separate legal entity formed for a specific transaction or investment purpose. In private markets, one common use is to aggregate a group of investors into a single entity that then owns an interest in an underlying company or asset.
An SPV is not automatically diversified, low-risk, liquid, or tax-efficient. Those characteristics depend on what the SPV owns, how it is financed, the governing documents, the sponsor, fees, investor rights, and the exit path.
How a Typical Private-Investment SPV Works
A sponsor or manager identifies a specific private investment opportunity.
A new legal entity is formed for that opportunity.
Investors subscribe for interests in the SPV and contribute capital.
The SPV deploys that capital into the underlying company, property, loan, or other asset.
Income, distributions, sale proceeds, and expenses flow through the SPV according to its governing documents.
Investors receive reporting and tax documents based on the legal and tax structure.
Why Sponsors Use SPVs
| Reason | What It Can Accomplish | What Investors Should Still Review |
| Single-deal access | Allows several investors to participate in one identified asset or company. | Concentration risk and the quality of the underlying opportunity. |
| Administrative simplicity | Keeps cap-table or ownership administration at the SPV level rather than adding many direct investors. | Manager authority, voting rights, and reporting practices. |
| Co-investment structure | Can give investors access to a deal alongside a fund, sponsor, or strategic partner. | Whether economics and rights differ from other investors in the transaction. |
| Defined strategy | Separates one investment mandate from a sponsor’s other funds or operating entities. | Whether the SPV can make follow-on investments, borrow, or change strategy. |
SPV vs. a Diversified Private Fund
A diversified private fund may own many portfolio companies, loans, or properties. An SPV may hold only one or a small number of investments. That difference matters because a single-asset structure can make the outcome more dependent on one company, one property, one borrower, or one exit event.
Recent SEC-filed disclosures describing SPV investments specifically warn that SPVs may hold a limited number of investments and may add another layer of fees and expenses. The exact risk depends on the structure, but investors should not assume that ‘private fund’ and ‘SPV’ imply the same diversification profile.
The 8 SPV Questions an Investor Should Ask
1. What exactly does the SPV own? Identify the underlying asset, security, debt instrument, property, or operating company.
2. Who controls the SPV? Review the manager, sponsor, removal rights, voting rights, and authority granted in the operating or partnership agreement.
3. What are the fees and expenses? Look for management fees, setup costs, administrative expenses, carried interest, performance allocations, legal costs, and expenses charged at the underlying investment level.
4. How long can my capital be tied up? Private investments are often illiquid and may restrict transfers or withdrawals for years.
5. Can the SPV raise more capital later? Understand capital calls, follow-on financings, dilution, default remedies, and whether additional commitments may be required or optional.
6. How are distributions calculated? Read the waterfall or distribution provisions and understand who gets paid, in what order, and after which fees.
7. What reporting will I receive? Ask about financial statements, performance updates, K-1s or other tax documents, valuation frequency, and material-event communications.
8. What happens if the investment fails or cannot be sold? A clear downside case is as important as the projected return case.
Concentration Risk Deserves Special Attention
One of the biggest advantages of an SPV—direct exposure to a specific opportunity—is also one of its biggest risks. A single-company or single-project SPV may not have other assets to offset a weak outcome.
Investor.gov notes that private-equity investments are commonly illiquid and may limit an investor’s ability to withdraw for several years. Concentrated SPVs can combine that illiquidity with a narrow asset base, so investors should size the commitment with the full portfolio in mind.
Layered Fees Can Change the Economics
An SPV can incur its own legal, administrative, accounting, banking, management, or performance-based fees. If the SPV then invests in another fund or vehicle, investors may also bear indirect expenses at the underlying level.
That does not automatically make the structure unattractive, but it means the headline return target should be evaluated after understanding every layer of fees and expenses that can affect net results.
Liquidity and Transfer Restrictions
Private SPV interests generally do not trade like public stocks. Transfers may be restricted by the operating agreement, securities laws, the underlying issuer, or the manager. A secondary sale may not be available when an investor wants liquidity.
Before investing, assume the capital may remain committed for the full expected holding period—and potentially longer if the underlying asset takes more time to exit.
Valuation Can Be Less Transparent Than in Public Markets
A privately held asset does not have a continuously quoted market price. The manager may rely on financing rounds, appraisals, discounted cash-flow models, third-party valuations, comparable transactions, or other methods.
Investors should ask how often valuations are updated, who approves them, whether an independent administrator or auditor is involved, and how unrealized values differ from actual cash distributions.
Documents to Read Before You Invest
Private placement memorandum or offering memorandum, if provided
Operating agreement, limited partnership agreement, or other governing document
Subscription agreement and investor questionnaire
Fee and expense disclosures
Capital-call and default provisions
Distribution waterfall
Transfer restrictions
Conflicts-of-interest disclosures
Tax-reporting expectations
Financial statements or due-diligence materials on the underlying investment
How Mack Capital’s Fund Services Connect to SPV Operations
Mack Capital states that its Fund Services division supports fund setup and structuring, investor reporting and K-1 delivery, legal/compliance coordination, audit support, accounting, and custody relationships. Those operational functions matter because the legal structure is only the beginning; investors also depend on accurate administration after the entity is formed.
For investors evaluating opportunities across private equity, real estate, credit, and other alternatives, the Mack Capital Investor Portal provides access to current and upcoming deals, offering materials, financial highlights, reports, tax documents, and portfolio information.
Sources and References
Mack Capital – Investor Portal
Investor.gov – Private Equity Funds
SEC Filing Example – Risks of Investments in Special Purpose Vehicles
Educational Notice
This article is general educational information and is not investment, securities, legal, accounting, or tax advice. Private investments can involve substantial risk, limited liquidity, loss of principal, complex fees, and long holding periods. Review offering documents carefully and consult qualified advisers before making an investment decision.
Frequently Asked Questions
Is an SPV the same as a private equity fund?
Not necessarily. A private equity fund may own multiple portfolio companies, while an SPV is often formed for a narrower purpose such as one company, one property, or one co-investment. Always review the governing documents and the actual holdings rather than relying on the label.
Are SPV investments liquid?
Usually not in the way public stocks are. Private SPV interests commonly have transfer restrictions and no active public market. Investors should be prepared to hold for the expected investment period and potentially longer.
Do SPVs always issue Schedule K-1s?
No. Tax reporting depends on the entity’s tax classification and underlying structure. Many partnership-taxed SPVs issue Schedule K-1, but other structures can produce different tax forms. The offering documents and fund administrator should explain what investors should expect.